Turnkey incorporation of a Sociedad Limitada (SL): obtaining an NIE, corporate structuring, notarisation, registration with the Registro Mercantil, bank account, taxes, accounting and licences.
Spain is one of the largest economies in the EU and is suitable for establishing a fully operational company with access to the European market. The jurisdiction is chosen for IT, e-commerce, trade, consulting, tourism, the restaurant business, real estate and other activities focused on clients and partners in Spain and the EU.
Prikhodko & Partners is one of the leading partners for Ukrainian businesses in matters of company registration and support in Spain. We help not merely to register an SL, but to prepare the company for full-scale operations: obtain an NIE, open a corporate account, complete KYC/AML, set up accounting and taxes, obtain the necessary permits and organise ongoing legal support.
During the consultation, we will determine the optimal business form, registration region, required documents, timeframes, launch budget and further steps after the company is established.
EU jurisdictions where we have provided legal support to businesses
8
lawyers specializing in international corporate law
4,7/5
our Google rating based on 1,150+ reviews from clients
Four decisions to make before registration
01
Business form
SL, sole proprietorship, a branch of a foreign company or another structure depending on liability, partners and the scale of operations.
02
Region and city
The tax framework is established at national level, but some permits, support measures, costs and practical procedures depend on the autonomous community and municipality.
03
Ownership structure
The shareholders, interests, administrator, powers, voting procedure, investment rights and profit distribution must be determined.
04
Operating model
Expected turnover, types of income, cross-border transactions, VAT, payments to owners, related companies, as well as office premises, personnel, agreements and licences are assessed.
SL, autónomo or branch: which form to choose
Form
When it is suitable
Key features
Sociedad Limitada — SL
Operating business, partners, employees, investment and regular commercial transactions
Separate legal entity, limited liability of shareholders, corporate tax and full corporate administration
Autónomo
Small personal practice, freelancing or testing a business model
No separate legal entity, personal liability and taxation of the individual’s income
Sucursal
Entry of an existing foreign company into the Spanish market
A branch is not a legal entity separate from the parent company, so the parent structure remains liable for its obligations
How a Sociedad Limitada is structured
Shareholders: from one founder — an individual or legal entity.
Administrator: a sole administrator, several joint or several administrators with several liability, or a board of directors.
Share capital: legally from €1, but the amount should be aligned with expenses and the business model.
Registered office: the company must have a domicilio social in Spain.
Name: must be confirmed in advance by the Registro Mercantil Central.
NIF: the company obtains a Spanish tax identification number.
Beneficial owners: the ownership structure and ultimate control are subject to disclosure.
Is it worth establishing an SL with €1 of capital?
The law permits share capital from €1. However, until the combined amount of share capital and the legal reserve reaches €3,000, the company must allocate at least 20% of its profit to the reserve. In the event of liquidation where assets are insufficient, the shareholders may be liable for the difference between the declared capital and €3,000.
Therefore, for a company that immediately plans to open an account, lease premises, hire employees or work with counterparties, it is often more practical to establish share capital of €3,000 or another economically justified amount.
What a foreign founder needs
Foreign individuals involved in establishing or managing a company usually require a Número de Identidad de Extranjero — NIE. It is used for notarial, tax, banking and other economic procedures in Spain.
If the founder is a foreign legal entity, its constitutional and registration documents, evidence of the representative’s authority, ownership structure and information on the UBO are additionally prepared. The documents may require an apostille, legalisation and sworn translation into Spanish.
For an individual
Passport, proof of address, NIE, information about professional experience, sources of funds and future activities.
For a legal entity
Registry extract, articles of association, resolution on participation in the Spanish company, power of attorney, group structure and information on beneficial owners.
For the bank
Business plan, financial forecasts, counterparties, countries of payments, sources of capital and evidence of the economic rationale of the structure.
01. Structure and NIE
We determine the shareholders, administrator, interests and share capital and arrange the required identification numbers.
02. Company name
We submit name options to the Registro Mercantil Central and obtain confirmation of availability.
03. Articles and capital
We prepare the Estatutos Sociales, determine the corporate purpose, management system and procedure for forming the share capital.
04. Notarial incorporation
The founders or their representatives sign the Escritura Pública de Constitución before a Spanish notary.
05. NIF and Registro Mercantil
We obtain the tax identification number and submit the company to the commercial registry at the location of its registered office.
06. Launch of operations
We arrange tax registrations, bank account, accounting, social security, employees and the required permits.
Company registration and commencement of operations are different stages
Once the SL is entered in the Registro Mercantil, the company legally exists, but additional steps may be required before a particular activity can begin.
Level
Examples of procedures
National
AEAT, NIF, Modelo 036, corporate tax, VAT, VIES/ROI, social security and financial licences
Autonomous community
Sector registrations, tourism, trade, healthcare, education, transport and regional support programmes
Municipality
Licencia de apertura, declaration of commencement of activity, permits for premises, renovation, signage or a terrace
Corporate taxes in Spain in 2026
The tax rate depends not only on the age of the company, but also on its turnover, type of activity, status, group structure and availability of a special regime.
Category
Rate in 2026
Conditions
Standard rate
25%
Applies where the company is not entitled to another rate
Microenterprise
19% / 21%
19% on the first €50,000 of the tax base and 21% on the remainder if the previous year’s turnover was below €1 million and no other special regime applies
Entidad de reducida dimensión
23%
For companies that meet the criteria of the special regime for small and medium-sized enterprises
New company
15%
The first tax period with a positive tax base and the following period — subject to statutory conditions
Certified empresa emergente
15%
The first profitable period and the following three periods, provided ENISA certification is obtained and the status is maintained
Standard IVA
21%
Rates of 10%, 4% or 0% apply to certain goods and services
The 15% rate is not automatically available to every startup
It is necessary to distinguish between an ordinary newly established company and an empresa emergente certified by ENISA. Certification assesses innovation, scalability, company age, turnover, structure, personnel in Spain and other criteria.
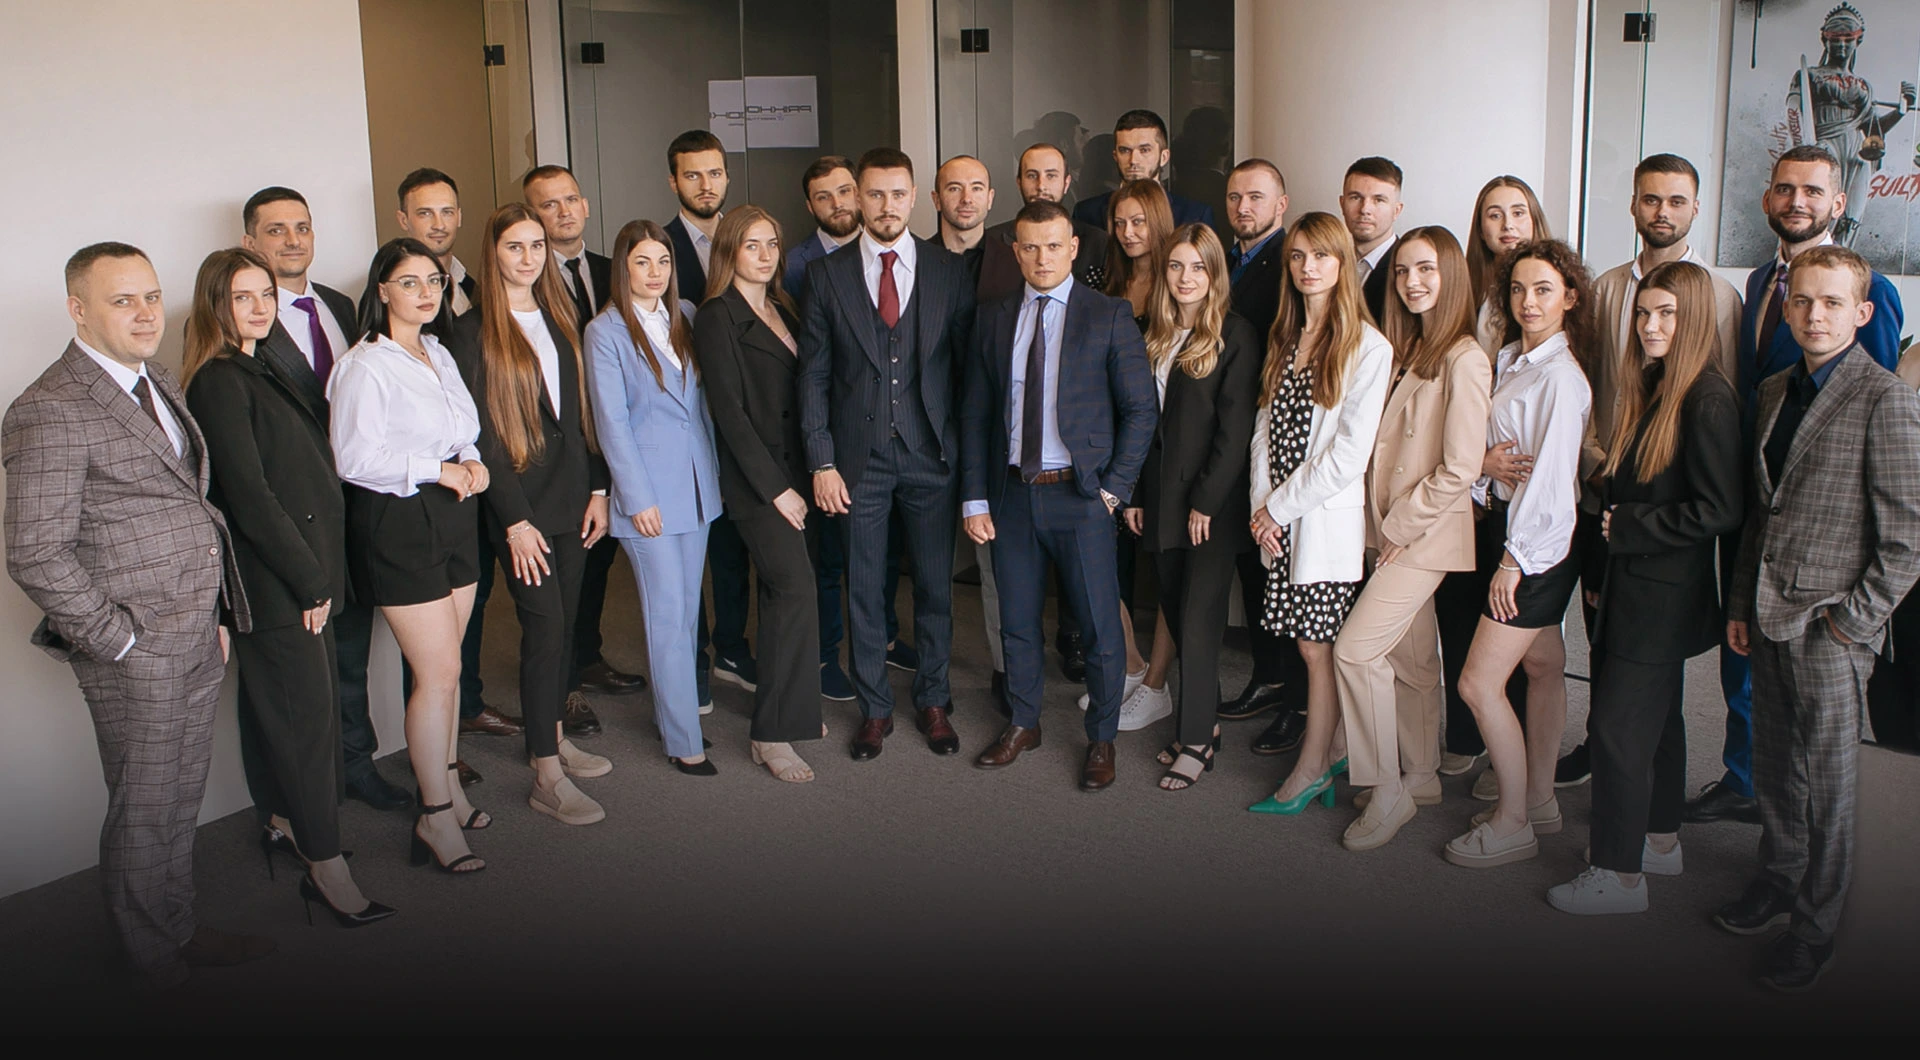
Prikhodko&Partners team of specialists providing legal support for business in Spain
The special regime for individuals relocating to Spain may allow certain income to be taxed at 24% up to €600,000. Income above this amount is subject to a 47% rate.
However, ownership of an SL alone does not guarantee application of the regime. The grounds for relocation, previous tax residence, the person’s role in the company, application deadlines and other statutory conditions must be reviewed.
Corporate account and bank KYC
Registration of an SL does not mean that an operating account will be opened automatically. The bank or payment institution separately reviews the company, shareholders, administrator, UBO, sources of funds and future payments.
For the account, we prepare:
a description of the product and business model;
the ownership structure and group of companies;
documents relating to the UBO and sources of funds;
contracts or information about future clients and suppliers;
the geography and purpose of payments;
financial forecasts and expected turnover;
an explanation of the business’s economic connection with Spain.
Company and residence permit: two separate legal processes
Registration of an SL does not in itself automatically grant the founder the right to reside or work in Spain. If the entrepreneur plans to relocate, the immigration strategy should be developed in parallel with the corporate strategy.
Innovative entrepreneurial project
Suitable for an innovative business of particular economic interest to Spain. ENISA assesses the applicant’s profile, business plan, financing, innovation and added value to the economy.
The law does not establish a universal minimum investment or mandatory number of jobs, but the project must be sufficiently substantiated.
Work por cuenta propia
May be used for traditional entrepreneurial and professional models that do not meet the criteria of an innovative project.
Professional qualifications, required permits, financing, project viability and the possibility of establishing the activity in Spain are reviewed.
The Golden Visa investment programme was discontinued for new applications from 3 April 2025. Company registration should not be presented as its automatic replacement: a residence permit requires compliance with the requirements of a separate immigration category.
Discuss launching a business in Spain with a lawyer
Describe your business model, composition of the founders and plans for operating in Spain. A lawyer will determine the optimal business form, the need for an NIE, bank account, tax registration and licences, and will prepare an action plan, list of documents, indicative timeframes and launch budget.
Expert in corporate and international corporate law. Specialises in establishing and structuring businesses in Spain and other EU countries, supporting SL registration, opening corporate accounts, tax planning and ongoing legal support for companies.
Frequently asked questions
Can a non-resident register a company in Spain?
Yes. A foreigner may be a founder and administrator of a Spanish SL. Identification documents must be prepared, the required Spanish tax or personal identification numbers obtained, and notarial, corporate and banking checks completed.
Can an SL be opened remotely?
In many cases, the main part of the procedure can be completed through a representative acting under a notarised power of attorney. However, the procedure for obtaining an NIE, executing the power of attorney, bank identification and signing documents depends on citizenship, structure and the requirements of the particular institutions.
Is an NIE mandatory?
A foreign individual who participates in notarial incorporation, becomes a shareholder or administrator of the company usually requires an NIE. For foreign legal entities, a Spanish tax identification number is obtained and a separate package of corporate documents is prepared.
What is the current minimum share capital for an LLC (SL)?
The “Crea y Crece” law allows a company (SL) to be registered with share capital from €1. However, the company will be required to allocate 20% of its annual profit to the legal reserve until the combined amount of share capital and reserve reaches €3,000.
Can every startup pay 15% for four years?
No. The extended regime for empresas emergentes requires ENISA certification and compliance with requirements concerning innovation, scalability, age, turnover, structure and presence in Spain. Without such certification, the general rules for newly established companies apply.
Among business representatives from Eastern Europe and the Black Sea-Caspian region
TOP-20 law firms in Kyiv according to the Ukrainian Business Award rating
Law firm "Prykhodko & Partners" received recognition and an honorable place in the ranking
Forbes NEXT 250
In 2024, the Law Firm "Prykhodko and Partners" was included in the list of 250 most promising small and medium-sized companies in Ukraine according to Forbes
EBA Member
We are members of the European Business Association, the company's CEO is the head of the Legal Committee of the Kharkov office
Do you need assistance with opening a business in Spain?
We work Monday - Friday from 9:30 to 18:00. If you leave a request after 18:00 on weekdays - we will contact you the next business day starting at 9:30.








 Telegram
 Viber
 WhatsApp

 Facebook
 Instagram